AI Market Strain: The Surging Costs of SSDs and RAM
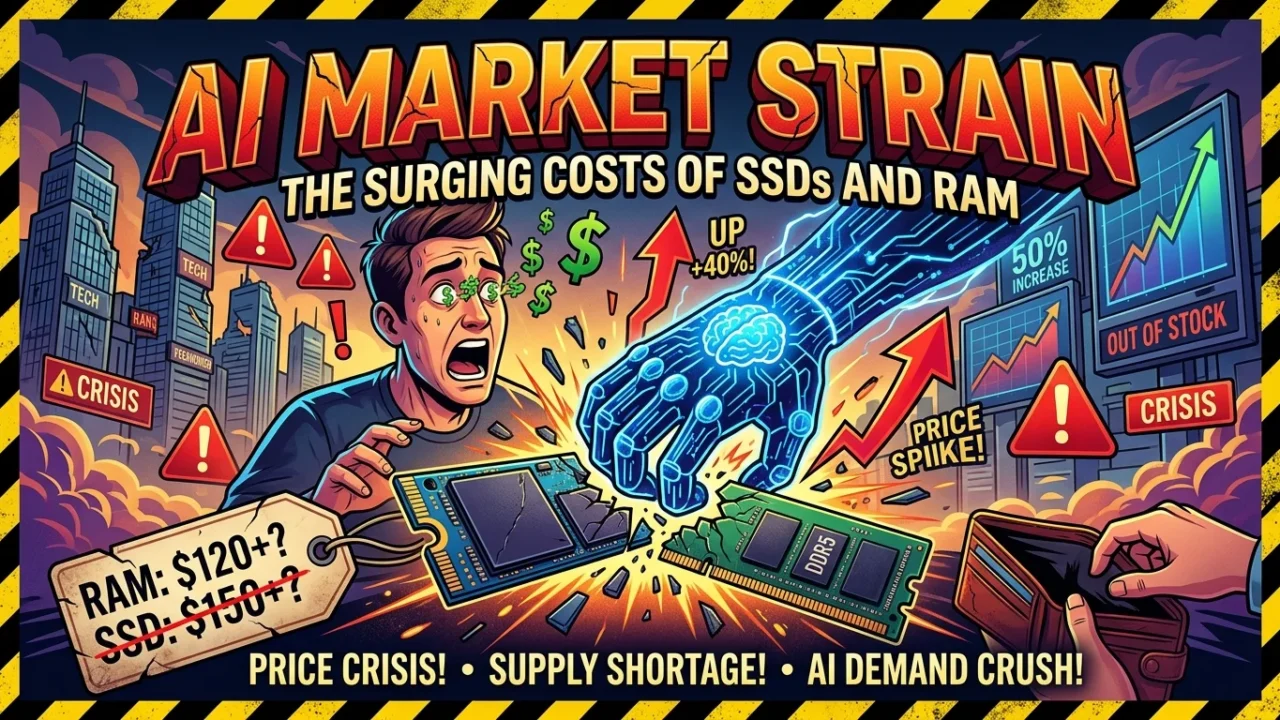
If you’ve priced a PC build in the last six months, you’ve felt it: the sticker shock on RAM and SSDs. What used to be the “cheap” part of a rig is now the line item that makes you pause, refresh the page, and wonder if you misread the price. This isn’t a blip. It’s a structural shift driven by AI.
Walk into any hardware forum and you’ll see the same story. Someone posts a planned build with 32GB of DDR5 and a 2TB NVMe, and the replies aren’t about timings or thermals anymore—they’re about whether it’s even worth buying right now. That’s how visible the pain has become.
What’s actually happening
AI data centers are eating memory. Not metaphorically—literally. Training and inference workloads need massive amounts of DRAM and high-performance NAND, and the big cloud operators are locking in supply with long-term contracts. That pulls capacity away from the consumer market and pushes prices up across the board.
The numbers are brutal. Industry estimates put DRAM price increases at more than 400% from the start of 2024 to the end of 2026. Combined DRAM and SSD prices are projected to be up well over 100% by the end of 2026. In some regions, retail DDR5 prices have jumped close to 500% since mid-2025.
SSDs tell a similar story. Enterprise 30TB TLC SSDs went from around $3,460 in Q3 2025 to $22,600 in Q3 2026—more than 6.5x in a year. That enterprise pressure bleeds into consumer pricing. Mainstream 2TB NVMe drives have seen annual increases well over 200%.
If you zoom out, this is the end of a two-decade trend where memory got steadily cheaper. That era effectively vanished in one brutal cycle as AI demand collided with limited fab capacity.
Why AI is crowding out your build
It’s not just “more servers.” It’s the type of memory AI wants.
-
HBM and server DRAM take priority at fabs. High-bandwidth memory for AI accelerators and server-grade DDR5 RDIMMs are higher-margin and in insane demand.
-
NAND capacity is being reallocated to enterprise SSDs and AI-optimized storage tiers.
-
Long-term contracts between cloud giants and memory makers reduce the pool of chips available for retail.
Memory makers—Samsung, SK Hynix, Micron—are expanding capacity, but new supply isn’t expected to come online in meaningful volume until 2029–2030. In the meantime, AI infrastructure and consumer PCs are bidding for the same wafers.
There’s also a product-mix effect. A single AI server can soak up hundreds of gigabytes of DRAM and multiple terabytes of fast NAND. Multiply that by thousands of racks at major cloud providers, and you can see why the “leftover” capacity for desktops and laptops shrinks so fast.
What this looks like at the checkout
Here’s the practical impact for builders and upgraders right now:
-
A 32GB DDR5 kit that cost ~$90–$100 in late 2025 is now in the $375–$459 range in mid-to-late 2026.
-
DDR4 hasn’t been spared. Spot prices for mainstream DDR4 chips jumped from about $12 to $37 by July 2026.
-
2TB NVMe SSDs that were $130 a year ago now sit around $300–$480 depending on model and region.
-
High-end PCIe 5.0 2TB drives are anchored near $380–$400 as a new “normal.”
If you’re building a 32GB DDR5 gaming rig today, you’re effectively paying 3–4x what that kit cost 12–18 months ago. That changes the entire value proposition of mid-range builds.
It’s not just enthusiasts feeling this. System integrators and OEMs are passing costs through, so prebuilts and laptops are seeing spec adjustments—smaller default SSDs, base RAM configurations that feel tight, and “upgrade later” language everywhere.
The mechanics behind the spike
To understand why prices are so sticky, you have to look at how memory is made and sold.
DRAM and NAND are produced on advanced fabs with long lead times. When demand shifts suddenly—like an AI boom—foundries can’t just flip a switch and retool. They have to plan new capacity, order equipment, and qualify processes, which takes years.
At the same time, AI customers sign multi-year contracts that guarantee them priority access. That gives memory makers predictable revenue, but it also means retail channels get whatever capacity is left after those contracts are filled.
Add in geopolitical factors—export controls, regional fab constraints, and supply-chain hedging—and you get a market that’s both tight and volatile. Prices don’t just drift up; they jump in steps as contracts renew and capacity gets re-allocated.
Who’s driving the demand
The usual suspects are behind most of the pressure:
-
Hyperscalers like Alphabet, Amazon, Microsoft, and Meta are pouring tens of billions into AI infrastructure. Their combined capital spending on AI-related hardware is a major chunk of the memory market.
-
AI chip vendors need ever-larger pools of memory to feed their accelerators. More parameters, bigger models, longer context windows—all of that translates directly into more DRAM and faster storage.
-
Enterprise adopters are starting to deploy AI workloads internally, from analytics to copilots, which adds another layer of demand on top of the cloud giants.
This isn’t a one-quarter spike. It’s a multi-year buildout that’s reshaping the entire memory landscape.
Is there any relief in sight?
Short answer: not soon. Analysts don’t expect prices to normalize until 2028 at the earliest. Some forecasts push meaningful relief closer to 2029–2030 as new fab capacity ramps. Until then, we’re in a “costly new normal” where AI factories dictate the baseline for memory pricing.
There are a few dynamics to watch:
-
Enterprise vs. consumer split: Data center contract prices will keep rising faster than retail, but retail still gets pulled along.
-
Product mix shifts: Expect more SKUs with smaller capacities and fewer “value” 2TB/4TB drives at old price points.
-
Upgrade cycles: Some builders will delay upgrades or lean harder on used markets, which could create odd pricing tiers between generations.
If you’re hoping for a quick return to 2024 pricing, that’s probably not in the cards. The market has structurally re-priced around AI demand.
What you can do right now
If you’re planning a build or upgrade, here’s how I’d think about it:
-
Buy only what you need today. Don’t over-provision RAM “just in case.” If 16GB gets you through your current games and apps, start there and add later if prices improve.
-
Consider last-gen platforms carefully. DDR4 boards and kits might look cheaper upfront, but DDR4 prices have also surged. Run the actual numbers for your region before assuming “older = better value.”
-
Watch for sales, but don’t wait forever. Deals still exist, but the floor has moved up. If you see a reputable 2TB NVMe near the lower end of the current range, that’s probably a good buy.
-
Prioritize GPU and CPU first. In a gaming build, the performance gap from a better GPU usually outweighs going from 32GB to 64GB of RAM. Allocate budget where it moves frames.
-
Track prices regionally. Some markets are hit harder than others. If you can import or time purchases around local promotions, you can sometimes beat the worst of the increases.
There’s also a mindset shift: treat memory as a “buy when you need it” component rather than a “max it out now” luxury. That’s a big change from the last decade, but it matches the reality of 2026.
The bigger picture
This isn’t just “prices go up, then down.” AI has rewired the memory market’s economics. The same wafers that used to flow mostly into phones, laptops, and DIY PCs are now heavily allocated to AI clusters with deep pockets and multi-year contracts.
For enthusiasts, that means rethinking what a “balanced” build looks like in 2026. It also means paying attention to memory pricing as a macro signal: when RAM and SSDs spike like this, it’s a sign that AI infrastructure is still in an aggressive expansion phase—and that consumer hardware is paying part of the bill.
You can argue about whether this is “fair.” From a market perspective, it’s exactly what you’d expect when a transformative technology suddenly demands a huge slice of a constrained resource. The question for builders isn’t whether prices will go back to 2024 levels—they probably won’t anytime soon—but how to adapt build strategies to this new reality.
What this means for rigandtech.com
On this site, we’ll treat memory and storage pricing as a core topic, not a side note. Expect regular updates on:
-
When specific RAM and SSD deals are actually worth grabbing
-
How much memory you really need for different gaming and productivity scenarios in 2026
-
Build guides that optimize around current pricing instead of outdated assumptions
The goal isn’t to scare you off building—it’s to help you spend smarter in a market that’s fundamentally changed. If you’re going to pay these prices, you should at least know exactly why, and how to get the most out of every dollar.